Industrial Wire Rod Market Remains Soft as Summer Slowdown Continues
Mid-August 2026 finds China’s industrial wire rod market stuck in the traditional summer lull. Production and mill inventories are both rising, social stocks are piling up, and downstream demand remains weak. The overall picture is one of ample supply meeting sluggish demand.
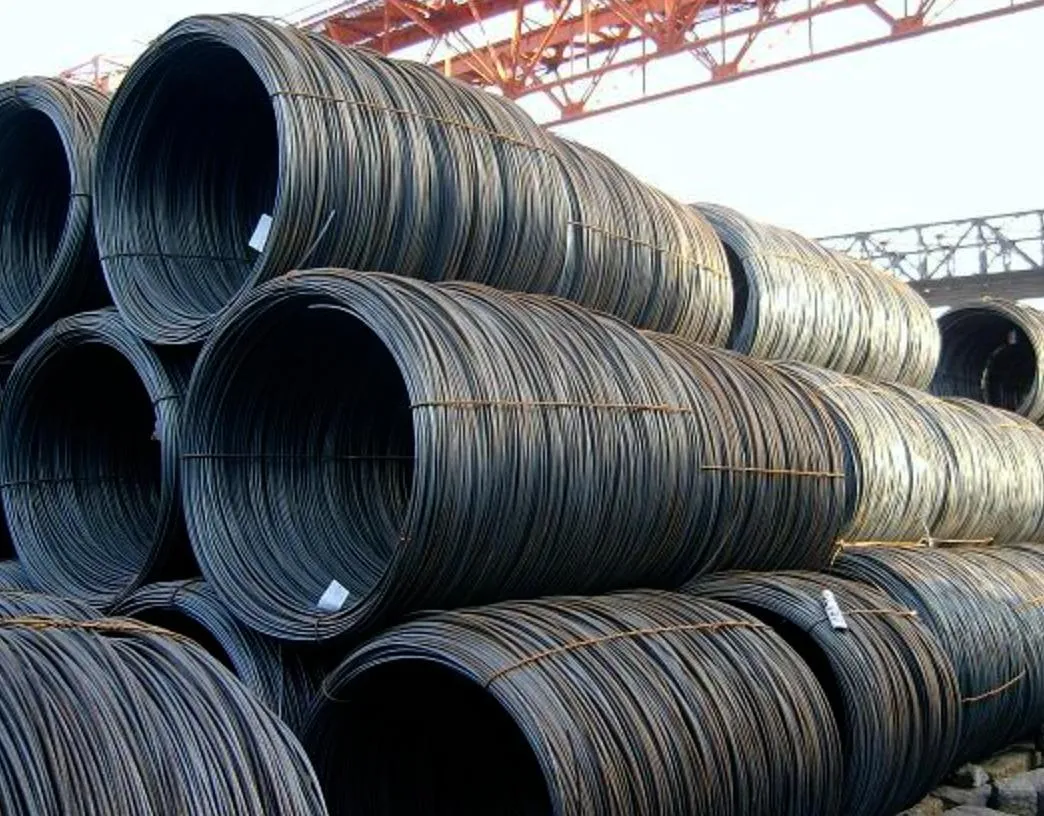
Industry data shows that the weekly output of 61 industrial wire rod producers came in at 1,499,050 tons, down 3.50 percent from the previous week. That is the first decline in about a month. Operating rates stood at 76.54 percent, and capacity utilization at 63.33 percent, down 1.12 and 2.3 percentage points respectively. But mill inventories actually rose against this trend, climbing to 769,100 tons, up 3.50 percent week-on-week. The pattern is a strange one: mills cut production, but stocks still went up.
The output cuts have not done much to ease inventory pressure. Social inventories of industrial wire rods hit 827,800 tons, up 67,500 tons or 8.88 percent from the previous week. Within that total, wire rod for drawing purposes stood at 461,500 tons, up 10.22 percent; cold heading steel wire rod at 317,100 tons, up 6.98 percent; and hard wire rod at 49,200 tons, up 8.85 percent. Inventories have been climbing for weeks, and the pace of accumulation is actually accelerating.
Demand is the weak link. Hot weather and the rainy season have curbed construction activity, making daily trading volumes erratic. On August 6, transaction volumes among sampled trading firms picked up slightly from the previous day, but overall activity remained sluggish. Five steel mills in Wu’an sold about 17,800 tons of drawing wire rod, barely up 300 tons from the day before. Buyers are out there, but they are pushing for lower prices. Sellers are holding firm. The standoff is slowing down actual orders.
Data from the National Bureau of Statistics shows that wire rod prices in the domestic distribution market fell again in early August. The price for Φ8-10mm HPB300 wire rod dropped to 3,244.5 yuan per ton, down 48.7 yuan from late July, a 1.5 percent decline. The downward price trend is starting to push some mills into maintenance shutdowns, but the supply cuts have not been deep enough to reverse the supply-demand imbalance.
On the trade policy front, there is a new development to watch. The US Department of Commerce published preliminary results on August 13, 2026, in its administrative review of anti-dumping duties on carbon and alloy steel wire rod from South Korea. The review covers imports under the order first imposed in 2018. POSCO is the only company being reviewed. The Commerce Department’s preliminary finding is that POSCO did not sell the subject merchandise at less than normal value during the review period. If this preliminary determination becomes final, imports during the review period would face no anti-dumping duties because the dumping margin would be zero. The final results are due within 120 days of the preliminary publication. If the preliminary determination is upheld, trade barriers on Korean wire rod exports to the United States could be lifted, potentially reshaping global trade flows.
Putting it all together, the industrial wire rod market is going through a seasonal adjustment phase. Production is down but inventories are still climbing. Demand is soft. Prices are likely to stay under pressure in the near term. Hot weather and rain are still affecting construction activity across much of the country. Trader confidence is fragile. In some regions, drawing wire rod prices have become the lowest in the country. The market is likely to remain weak and volatile in the near term, but a floor of support is still holding.